BUSINESS
The 10-Year at 5% Leaves the Treasury Paying Up
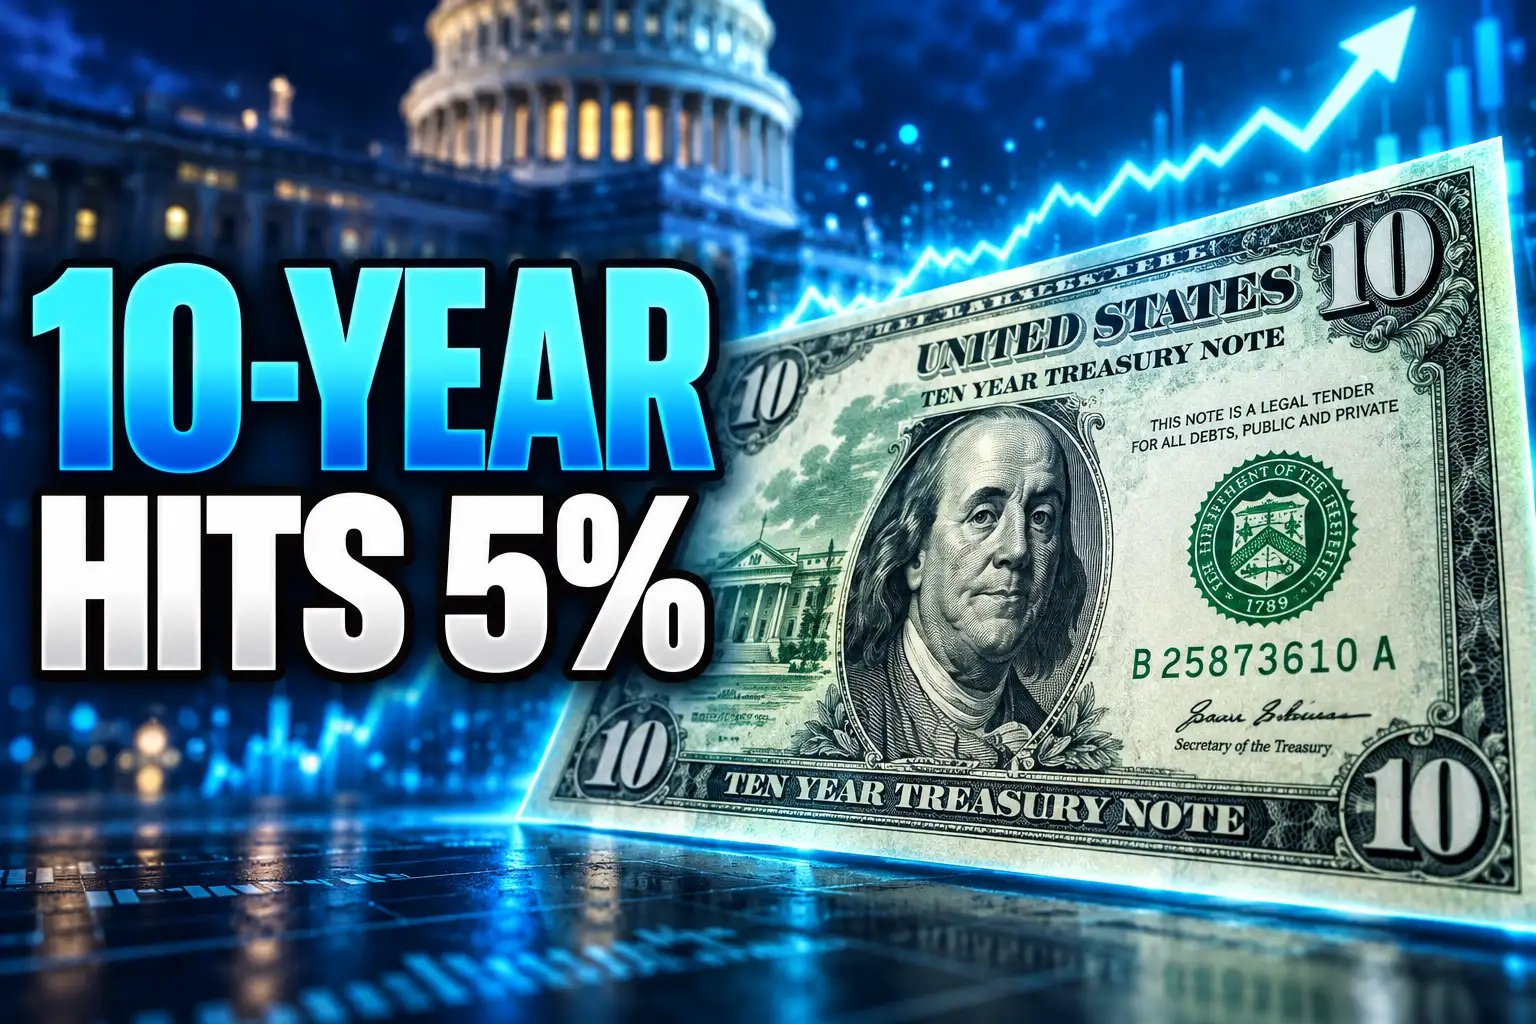
The 10-year yield sits above 5% as the Fed prepares to hike, turning a $40.10 trillion debt book into the borrower that actually pays.

The 10-year Treasury yield sat at 5.004% before 5 a.m. Eastern on Wednesday, a day after Tradeweb printed a 5.041% high, the highest since 2007. The Federal Reserve announces its September decision at 2 p.m. ET, with CME FedWatch putting a quarter-point hike at 92.5%.
The overnight vote is almost fully priced. The borrower already living with a 5% coupon is the United States Treasury.
The 10-Year Already Did the Tightening
Yields and prices move in opposite directions, and one basis point equals 0.01%. The 20-year note was unchanged at 5.409% in Wednesday’s early tape, and the 30-year was unchanged at 5.372%. The 2-year, which tracks the path of the funds rate, was near 4.68% on Tuesday.
The daily 10-year constant-maturity yield had already climbed about 100 basis points over the past year before this week’s break of 5%. Arif Husain, head of global fixed income at T. Rowe Price, said a 5% 10-year, and eventually a 6% yield, remain well within the range of possible outcomes, citing heavy sovereign supply, inflation that has not rolled over, and long bonds that still look expensive to him.
THE TREASURY CURVE BEFORE THE VOTE
| Instrument | Level | Context |
|---|---|---|
| Fed funds target | 3.50% to 3.75% | A hike would move the range to 3.75% to 4.00% |
| Effective funds rate | 3.63% | Last print into the meeting |
| 2-year note | 4.68% | Tuesday, sitting above the current ceiling |
| 10-year note | 5.004% | 4:30 a.m. ET Wednesday, after a 5.041% Tuesday high |
| 20-year note | 5.409% | Unchanged in Wednesday morning trade |
| 30-year bond | 5.372% | Unchanged in Wednesday morning trade |
Money markets, using LSEG’s read of futures, priced 91% odds of a 25-basis-point rise on Wednesday and a total of 94 basis points of extra tightening over a 12-month horizon, almost four quarter-point moves. Deutsche Bank’s look at the last 12 proper hiking cycles since the early 1960s found the 10-year rose about 114 basis points, on average, in the year after a cycle started. In only one of those cycles, the 2004-06 “measured pace” years, did the 10-year fall in the first year.
That history sits badly next to a long end that has already done most of a typical first-year backup. The funds rate is still the headline. The 10-year is the rate that prices mortgages, corporate debt, and the Treasury’s own refunding.
A $40 Trillion Borrower Rolls Into 5% Coupons
Joint Economic Committee Republicans, using Treasury data through September 3, put gross national debt at $40.10 trillion. Debt held by the public was $32.42 trillion. Intragovernmental debt was $7.68 trillion. The pile is $2.67 trillion higher than a year earlier, or $297,522 per household.
THE FISCAL TAB
- The coupon on the book: The average interest rate on total marketable debt was 3.475% in August, against 3.415% a year earlier and 1.458% five years earlier.
- What comes due: About 33 percent of publicly held marketable debt is set to mature within 12 months, so a large share of the book will reprice near today’s curve, not the old 1% coupons.
- The mix: Notes were $16.21 trillion, or 50.02% of public debt outstanding in August, with bills at $7.25 trillion (22.36%) and bonds at $5.51 trillion (17.01%).
- The cash cost: The Peter G. Peterson Foundation’s tally of Treasury budget data shows interest payments through July of $931 billion in fiscal 2026, up 10.6% from $842 billion in the same stretch of fiscal 2025.
Interest is already the third-largest federal outlay in that accounting, behind Social Security and Medicare. The Congressional Budget Office projects net interest of $1.0 trillion in 2026, rising to $2.1 trillion in 2036, or $16.2 trillion over the decade if current law holds. Relative to the economy, interest costs would reach 3.2% of GDP this year, above the previous high set in 1991. As a share of federal revenues, they were 18.5% by the end of last year.
Treasury Secretary Scott Bessent increased buybacks of long-dated notes from September through early November. The backup in yields continued anyway. A 25-basis-point move in the overnight rate does not refinance a third of a $32.42 trillion public book. A 5% 10-year does.
Warsh Drew the Line at Jackson Hole
Kevin Warsh is in his third Federal Open Market Committee meeting as chair, after taking the job in May. Policymakers have held the 3.50% to 3.75% target at all five FOMC meetings this year. The last hike was in July 2023. At the July 28-29 meeting the committee voted 9-3 to stand still, with Beth Hammack, Neel Kashkari, and Lorie Logan preferring a quarter-point increase.
On August 28, in his first Jackson Hole address as chair, Warsh put the inflation miss on the institution he now runs. The 12-month PCE index, the Fed’s preferred gauge, stood at 3.7%, and the six-month change was 4.1%. He said 54% of the 199 items in the PCE basket had risen more than 3% over 12 months, below the post-pandemic high near 77% and still well above the 32% share in the two decades before the pandemic.
The responsibility for 65 months of sustained, elevated inflation sits squarely with the central bank. And that is where it belongs.
Kevin Warsh, Federal Reserve Chairman, in his keynote remarks at Jackson Hole
He set a test, not a date, in those keynote remarks at Jackson Hole. “Here is my standard: We must be confident that underlying inflation is moving to our objective, clearly and at sufficient speed. Otherwise, we have work to do.” He called the 2% PCE target “firm” and “fixed,” said short-term rates are the “predominant tool,” and argued that this summer’s better-than-feared readings did not show that underlying trends had “meaningfully improved.”
Hike odds were about 33% a month before Wednesday. After the speech, futures moved the September meeting into coin-flip, then majority, territory. Friday’s inflation print finished the job.
Why a Hold Would Cost the Fed More Than a Hike
Brent Wilsey, chief investment officer at Wilsey Asset Management, said a pause would land as a shock in a market that has spent two weeks pricing 25 basis points as the base case.
If the Federal Reserve were to keep rates steady Wednesday, that could surprise stocks, and surprises are rarely received well in markets. It could also damage the Fed’s credibility, and reignite concerns that the central bank is caving to political pressure to keep rates steady.
Brent Wilsey, chief investment officer, Wilsey Asset Management
The Trump administration has pressed the Fed to lower rates. That pressure is public. The bond market’s pressure is a 5.041% 10-year. Skipping a hike that futures put at 92.5%, with only a 7.5% chance of an unchanged target, would tell dealers the committee is more sensitive to the White House than to a 3.7% PCE print.
Jonathan Pryor, co-head of FX dealing at Marex, said the Fed is “moving into a new phase of monetary policy.” Earlier in the year it looked like a cutting cycle that might last six or twelve months, he wrote. “Now it feels like the tables have turned.” Central banks, he said, are trying to tackle inflation that is still largely a supply-side problem while global bond markets are under a spotlight.
A 25-basis-point increase is small next to the backup already in long yields. A hold would not be small. It would ask investors who just marked 5% on the 10-year to believe the chair did not mean the standard he set on August 28.
Mortgages Cleared 7% Before Anyone Voted
The funds rate sets overnight money. Home loans, corporate refinancings, and 10-year refundings take their cue from the long end. Higher yields have already pushed the 30-year fixed mortgage rate back above 7%, before the committee votes.
WHAT A 5% 10-YEAR ALREADY CHANGES
- New mortgages: A 30-year loan above 7% raises the monthly payment on every purchase and cash-out refinance closed off the current coupon, even if the Fed later holds.
- Treasury refunding: Notes are half the public book. Replacing maturing 3% paper with 5% paper locks in a higher cash interest bill for a decade.
- Corporate credit: Investment-grade and high-yield new issue both reprice off the Treasury curve, so capex and buybacks that need the bond market get more expensive in the same tape.
- Duration assets: Equity valuations that rest on cash flows years out get discounted at a higher risk-free rate, which is why rate-sensitive names sold off as the 10-year broke 5%.
That transmission is why the live argument on trading desks is not whether 25 basis points land at 2 p.m. It is whether Warsh, who has said he wants a quieter Fed and less forward guidance, describes a one-move adjustment or a path. CME FedWatch still assigned a 49.7% chance of two 25-basis-point increases by year-end, taking the target to 4.00% to 4.25%, a 28.9% chance of three increases to 4.25% to 4.50%, and a 20% chance that Wednesday is the only hike through December.
August CPI Held at 3.4% as Energy Rebounded
The Bureau of Labor Statistics August consumer price index report, released September 11, showed the all-items index up 0.4% on the month after 0.1% in July, and up 3.4% over 12 months, matching July’s annual rate. Gasoline rose 3.9% in August and accounted for over one third of the monthly all-items increase. Energy was up 2.1% on the month and 16.3% over the year. Gasoline was up 27.4% over 12 months. Food rose 2.7% over the year. Core prices, all items less food and energy, rose 0.3% in August and 2.4% over 12 months.
Oil remains above $100 a barrel, with Brent crude near $108 in Wednesday trade after sitting at $106.12 on September 8, against $65.44 a year earlier. The Iran war has kept a premium in crude since late February, and gasoline is where that premium hits the CPI. Core at 2.4% is closer to the Fed’s 2% goal than the headline. The gasoline line is why the headline has not been allowed to settle.
HOW THE SEPTEMBER HIKE GOT LOCKED IN
- July 28-29, 2026: The FOMC holds 3.50% to 3.75% on a 9-3 vote, with three members preferring a hike.
- August 28, 2026: Warsh tells Jackson Hole that 65 months of high inflation belong to the Fed and that the committee has “work to do” if underlying prices are not moving to 2% at sufficient speed.
- September 11, 2026: August CPI holds at 3.4% annually, the monthly rate jumps to 0.4%, and gasoline supplies more than a third of that increase.
- September 15, 2026: The 10-year prints 5.041% on Tradeweb, the highest since 2007.
- September 16, 2026: The 10-year sits at 5.004% at 4:30 a.m. ET. CME FedWatch prices a 25-basis-point hike at 92.5%, with the statement and projections due at 2 p.m. ET and Warsh’s press conference at 2:30 p.m.
That sequence is the cutting-cycle bet being unwound in public. Pryor’s “tables have turned” line is the same story in a dealing-room sentence.
Money Markets Price 94 Basis Points of Extra Tightening
If the committee delivers 25 basis points, the target becomes 3.75% to 4.00%, a one-year high for the overnight rate and the first increase in more than three years. LSEG’s 94 basis points over 12 months would take policy toward the mid-4s if the path is realized. Husain’s 6% 10-year is the long-end version of that same risk: booming supply, inflation that has not died, and a term premium that no longer assumes a friendly buyer at every auction.
The Summary of Economic Projections, including the rate dots, lands with the decision. Warsh has spent his first hundred days arguing against the old habit of telling markets the next three moves. That makes the press conference the document. A chair who repeats the Jackson Hole test will keep 5% as a floor under the 10-year. A chair who leans on core at 2.4% and a 9-3 July hold will invite a short-covering rally that the fiscal calendar can still fade.
Washington wanted cheaper money. The 10-year is offering 5.004% instead, and about a third of the public marketable book has to take whatever coupon the market is showing. The 2 p.m. vote can bless that backup. It cannot unwind it.
Disclaimer: This article is news reporting and analysis of Treasury yields, federal borrowing costs, and the Federal Reserve’s September policy meeting, and it is for information only. It is not investment advice, a recommendation to buy or sell bonds, stocks, or any other security, and it is not a forecast of the FOMC’s vote or of future interest rates. Readers who are making portfolio, mortgage, or business-borrowing decisions should consult a qualified financial adviser, accountant, or licensed broker who can weigh their own facts. Yields, probabilities, debt totals, and inflation readings reflect the sources cited as of September 16, 2026, and all of those figures can move after the 2 p.m. ET announcement.

Iran’s Hormuz Offer Puts a Seven-Day Clock on Washington

The 10-Year at 5% Leaves the Treasury Paying Up

Zero Opens Its AI CRM After a $10.3 Million Seed

Zverev Beats Shelton to Settle a Six-Year New York Debt

Diablo 4’s Annual Expansion Promise Ends After Two Packs

How to Dress for an Interview Men – The Dos and Don’ts of Professional Attire

Miami-Dade Sent Rockstar a Vice City Wish List

HP Wraps NVIDIA’s Chip in OmniBooks After a Share Rally

Stolen Logins Now Talk to the Company’s AI Agents

Australia Offers a Feed Switch and a Duty on Chatbots
-
 BUSINESS3 years ago
How to Dress for an Interview Men – The Dos and Don’ts of Professional Attire
-
 GAMING4 weeks ago
Miami-Dade Sent Rockstar a Vice City Wish List
-
 BUSINESS3 weeks ago
HP Wraps NVIDIA’s Chip in OmniBooks After a Share Rally
-
 NEWS3 weeks ago
Stolen Logins Now Talk to the Company’s AI Agents
-
 NEWS3 weeks ago
Australia Offers a Feed Switch and a Duty on Chatbots
-

 BUSINESS3 weeks ago
Canada’s Matched Tariffs Expose a Supply Chain It Shares
-

 NEWS3 weeks ago
Pinterest Turns a Shopping Guide Into a Q4 On-Ramp
-
 BUSINESS2 years ago
How Much Do Gymshark Athletes Make – The Income and Sponsorship of the Popular Fitness Brand Ambassadors